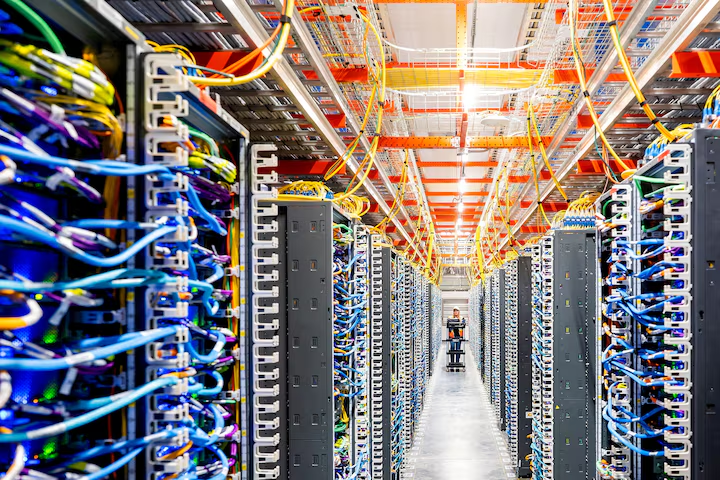
Fuel-cell technology is gaining momentum among US hyperscalers racing to expand data centres for the artificial intelligence (AI) boom, as electricity grid constraints make it increasingly difficult to secure reliable power quickly.
Energy research firm Rystad Energy projects that investment in fuel cells for data centres will rise to approximately $30 billion by 2030, compared with $2.8 billion in 2025.
The technology offers data-centre developers an alternative source of on-site electricity, potentially reducing their dependence on grid connections that can take years to establish.
What Are Fuel Cells?
Fuel cells generate electricity through a chemical reaction between a fuel, such as natural gas or hydrogen, and oxygen. Unlike conventional power generation, they convert the fuel’s energy directly into electricity rather than burning it to produce power.
Bloom Energy uses solid-oxide fuel-cell technology designed to operate with 100% pure hydrogen, while FuelCell Energy employs molten-carbonate technology that supports hydrogen blends of up to 40%. Both companies offer fuel-flexible systems.
Ronaldo’s 982nd Career Goal Sparks Controversy as 1,000-Goal Milestone Nears
Fuel cells also produce lower local emissions than conventional gas-fired generation because they avoid combustion within the fuel-cell stack, although their overall environmental impact depends on the fuel used and how it is produced.
Why Is Demand Increasing?
AI data centres require enormous amounts of electricity to operate computing equipment and cooling systems around the clock. As demand expands, securing sufficient power has become a major challenge for developers.
According to Rystad estimates, connecting large electricity loads to the US grid can take between three and six years, encouraging companies to consider on-site generation.
Bloom Energy chief executive KR Sridhar highlighted the speed of deployment during a post-earnings call on Thursday.
“We announced our first project with Oracle and delivered power to their Utah site in less than two months,” Sridhar said.
He added that Bloom was achieving similar progress with Nebius in New Jersey, where the company secured planning board approvals for its fuel cells within three months of signing the contract.
Rystad estimates that around 40% of projected US data-centre capacity in 2030 could pursue dedicated on-site power rather than depend entirely on the electricity grid.
Bloom Energy and FuelCell Energy Position for Growth
Bloom Energy has reported strong financial growth amid rising demand for its fuel-cell systems.
The company’s third-quarter revenue surged 138% to $1.24 billion, while it posted a net profit of $250.3 million, compared with a loss of $23.1 million in the same period a year earlier.
Bloom also raised its 2026 revenue forecast to between $4.4 billion and $4.6 billion.
US technology giant Oracle intends to procure up to 2.8 gigawatts (GW) of Bloom fuel-cell systems, of which 1.2 GW has been contracted.
FuelCell Energy is also expanding its focus on data centres as developers prioritise the speed and reliability of electricity supply.
“Time to power has really become as important as cost of power,” FuelCell Energy chief executive Jason.
The company expects data centres and related businesses to account for between 75% and 85% of its business within two to three years, up from approximately 25% to 30% currently.
Rystad estimates the industry’s order book at roughly 9 GW, including framework agreements involving Oracle, AEP, Equinix and Brookfield. However, such agreements do not necessarily represent firm orders for the full stated capacity.
Can the Industry Expand Fast Enough?
Meeting projected demand will require significant expansion in manufacturing capacity.
Rystad expects annual fuel-cell manufacturing capacity to increase to 4 GW by 2030, from approximately 1.8 GW currently.
Bloom Energy chief commercial officer Aman Joshi said the main challenges for large-scale projects often involve site readiness, permitting and supporting infrastructure rather than the technology itself.
“For 100 MW-plus projects, the biggest determinants of timeline are typically site readiness, permitting, and supporting infrastructure, not the fuel-cell technology itself,” Joshi.
Projects still require gas connections, permits, transformers and switchgear, all of which can delay deployment even when fuel-cell equipment is available.
Fuel cells can complement grid electricity and compete with other on-site generation technologies, offering data-centre operators another option for securing dependable power.
The sector’s growth will depend on suppliers’ ability to expand manufacturing, developers’ capacity to complete supporting infrastructure and the economics of fuel-cell systems compared with alternative power sources.
As AI infrastructure expands, the ability to secure electricity quickly is becoming a central consideration in data-centre development, potentially creating a substantial market for on-site energy technologies over the remainder of the decade.